Selling one Orange County home while preparing to buy another requires more than choosing a list price. A few early decisions—about timing, financing, preparation, contingency terms, and proceeds—can help protect your purchasing power and keep the next move on a steadier track. Start with a coordinated plan before the first listing photo is taken.
A Move-Up Sale Is Really Two Connected Transactions
Moving up can mean gaining a larger layout, a different property type, additional outdoor space, or simply a home that better matches the way you use it today. In Orange County, where listing conditions can vary noticeably between cities, price ranges, and property types, the sale side and purchase side need to be planned together. The strongest strategy is rarely “sell first” or “buy first” in the abstract; it is the sequence that fits your cash position, financing options, desired timeline, and comfort with uncertainty.
Begin by separating the emotional wish list from the financial guardrails. It is useful to identify the neighborhoods, home features, and property conditions that matter most, but it is equally important to define a maximum purchase payment, down payment target, reserve fund, and preferred closing window. Those numbers influence how aggressively you can prepare and price the current home—and how confidently you can write an offer on the next one.
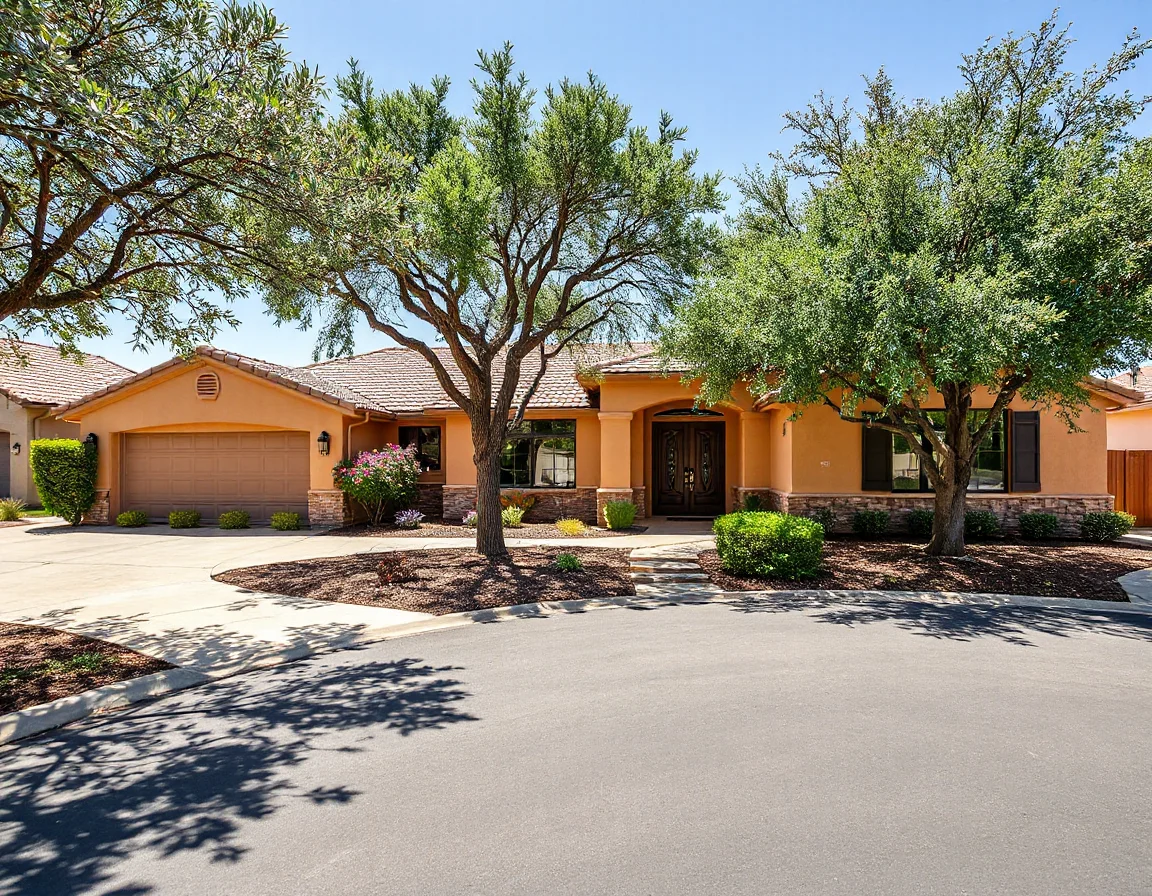
Orange County inventory can reward preparation. A home that looks comparable online may differ materially in condition, homeowners association costs, lot configuration, renovation quality, and location within the community. Having a clear purchase brief before launching your listing prevents a rushed search after accepting an offer. It also makes it easier to recognize a suitable opportunity when it appears.
Before setting a list date, map three dates on one calendar: your preferred sale closing, your target purchase closing, and the latest date you could comfortably move. The space between them is often more valuable than an ambitious list-price estimate.
Decision 1: Choose Your Purchase Strategy Before You Go Live
The first major decision is how you intend to secure the next property. Some sellers prefer to list and accept an offer before shopping seriously, while others investigate bridge financing, a home equity line of credit, or a contingent purchase structure. Each route has tradeoffs. Selling first may clarify available proceeds, but can create a temporary housing need. Buying first may offer more control over the move, but requires a realistic plan for carrying costs and sale risk.
Speak with a qualified lender early enough to compare scenarios rather than relying on a single estimate. Ask for illustrations that account for your current mortgage payoff, projected net proceeds, down payment choices, taxes and insurance, homeowners association dues where applicable, and the possibility of overlapping payments. A lender can also explain whether your financing profile supports a contingent offer, recast option, or another approach suitable for your circumstances.
On the sale side, review likely net proceeds rather than focusing only on the headline sale price. Existing loan balances, closing costs, repair credits, property taxes, moving expenses, and any buyer concessions can affect the funds available for the next purchase. A detailed net sheet turns a broad goal into a workable range.
Decision 2: Price for the Market You Have, Not the One You Remember
Recent sales are useful, but they are not a substitute for current competition. The homes a buyer can tour this week often set the practical context for your listing. Evaluate active listings, pending sales, and closed transactions with attention to condition, square footage, layout, outdoor areas, parking, association rules, and updates. In condo communities, even similar floor plans can command different attention depending on exposure, floor level, maintenance, and monthly dues.
Pricing is also a timing tool. A well-supported launch price can concentrate attention and help establish a cleaner negotiating position early in the listing period. A price that is difficult to support may extend market time, complicate a contingent purchase plan, and make the eventual move feel less predictable. The right number should be based on evidence, presentation, and the terms you need—not on a target amount alone.
Consider what terms have value to you beyond price. A higher offer with a short timeline may not be preferable if you need time to locate your next home. Conversely, a buyer who offers a flexible closing or temporary post-closing occupancy agreement may make the overall transition easier. Review the complete offer package: financing strength, contingencies, deposit, requested credits, closing date, and any personal property requests.
Thoughtful preparation supports pricing. Address visible deferred maintenance, simplify rooms for photography, organize disclosures, and decide in advance which improvements are worth completing. Not every project returns its cost, especially if it delays your launch. Focus on repairs or presentation changes that help buyers understand the home’s condition and potential without turning the sale into an open-ended renovation.
Decision 3: Protect the Gap Between Selling and Buying
The timing gap is often the most challenging part of a move-up sale. Your current buyer may need a defined closing date, while the next seller may prefer a different schedule. Instead of treating this as a last-minute logistical issue, identify backup options while your home is still being prepared. These might include a negotiated rent-back, a short-term rental, storage, or a plan to stay with trusted contacts if that arrangement works for you.
Build flexibility into the offer strategy for your next home whenever possible. A purchase contingency can protect you from owning two properties at once, but it may make an offer less competitive in some circumstances. A non-contingent offer carries more responsibility and should only be considered after reviewing financing, reserves, and sale probability carefully. There is no universally correct answer; the goal is to understand the consequence of each choice before signing.
A move-up plan should include a “Plan B address.” Even if you never use it, knowing where you can land for a short period can make sale and purchase negotiations far less pressured.
Decision 4: Define What Must Stay Liquid
It can be tempting to direct every available dollar from the sale toward the next down payment. However, keeping a reserve can be practical after a move. New ownership often brings immediate expenses: moving services, utility transfers, window coverings, small repairs, furnishings, landscaping adjustments, or association-related fees. A reserve also gives you more room to handle an unexpected appraisal, inspection negotiation, or timing change without revisiting the entire plan.
Work with appropriate financial and tax professionals for guidance tailored to your circumstances, particularly if you have investment assets, a prior rental history, substantial capital gains, or questions about how the sale may affect your broader finances. The real estate transaction is one part of a larger financial picture. Clear advice before listing can prevent decisions made under the pressure of contract deadlines.
Decision 5: Make the Next Search Specific and Ready
Once the sale plan is underway, keep the purchase search disciplined. Create a short list of non-negotiables, strong preferences, and features that would be nice but are not essential. Consider practical details such as commute routes, parking, outdoor maintenance, homeowners association documents, local services, recreation access, and the likely upkeep of the property. Touring with a defined framework helps you compare homes fairly rather than reacting only to a polished first impression.
For a move-up purchase, the best fit is not always the largest home or the most recently renovated one. It is the property whose location, condition, monthly costs, layout, and long-term maintenance align with your plan. Take time to review disclosures, inspections, title matters, and association materials with the same care you used when evaluating the financial side of the move.
The most protective move-up strategy is a coordinated one. By deciding how you will finance the transition, setting a market-aware price, planning for timing gaps, preserving appropriate liquidity, and searching with clear priorities, you can approach both transactions with more control. The next purchase should feel like a considered step forward—not a deadline created by the sale of your current home.